All Categories
Featured

How to Secure Impaired Risk Insurance
Table of Contents
Understanding how provider monetary strength and underwriting cravings relate to each other is likewise essential context our resource on what an insurance provider's AM Finest rating means covers the financial strength measurement, and our resource on how do insurance coverage brokers earn money covers why independent broker access to multiple providers regularly produces better outcomes after a decline than applying to a single provider based on name acknowledgment.
Simplified issue policies, which use health concerns without a complete paramedical exam and prescription database evaluation, are more accessible for profiles that struggle in completely underwritten lanes while still supplying significant death benefit amounts at defined premiums. Surefire issue policies, which need no health information, provide final expense coverage with graded benefits for the initial period.
Return-of-premium term structures offer a different risk/reward proposal that periodically opens underwriting lanes for profiles where basic term is challenging our resource on term life insurance with return of premium covers this option. And our resource on is Guardian Life an excellent insurance coverage company covers one carrier known for favorable permanent underwriting in specific complex-profile categories. Underwriting guides for typical disqualifier classifications and alternative coverage structures. Specialized underwriting resources for specific conditions, visa profiles, and coverage timing choices.
, is a possibility for those who think they might have trouble qualifying for protection.
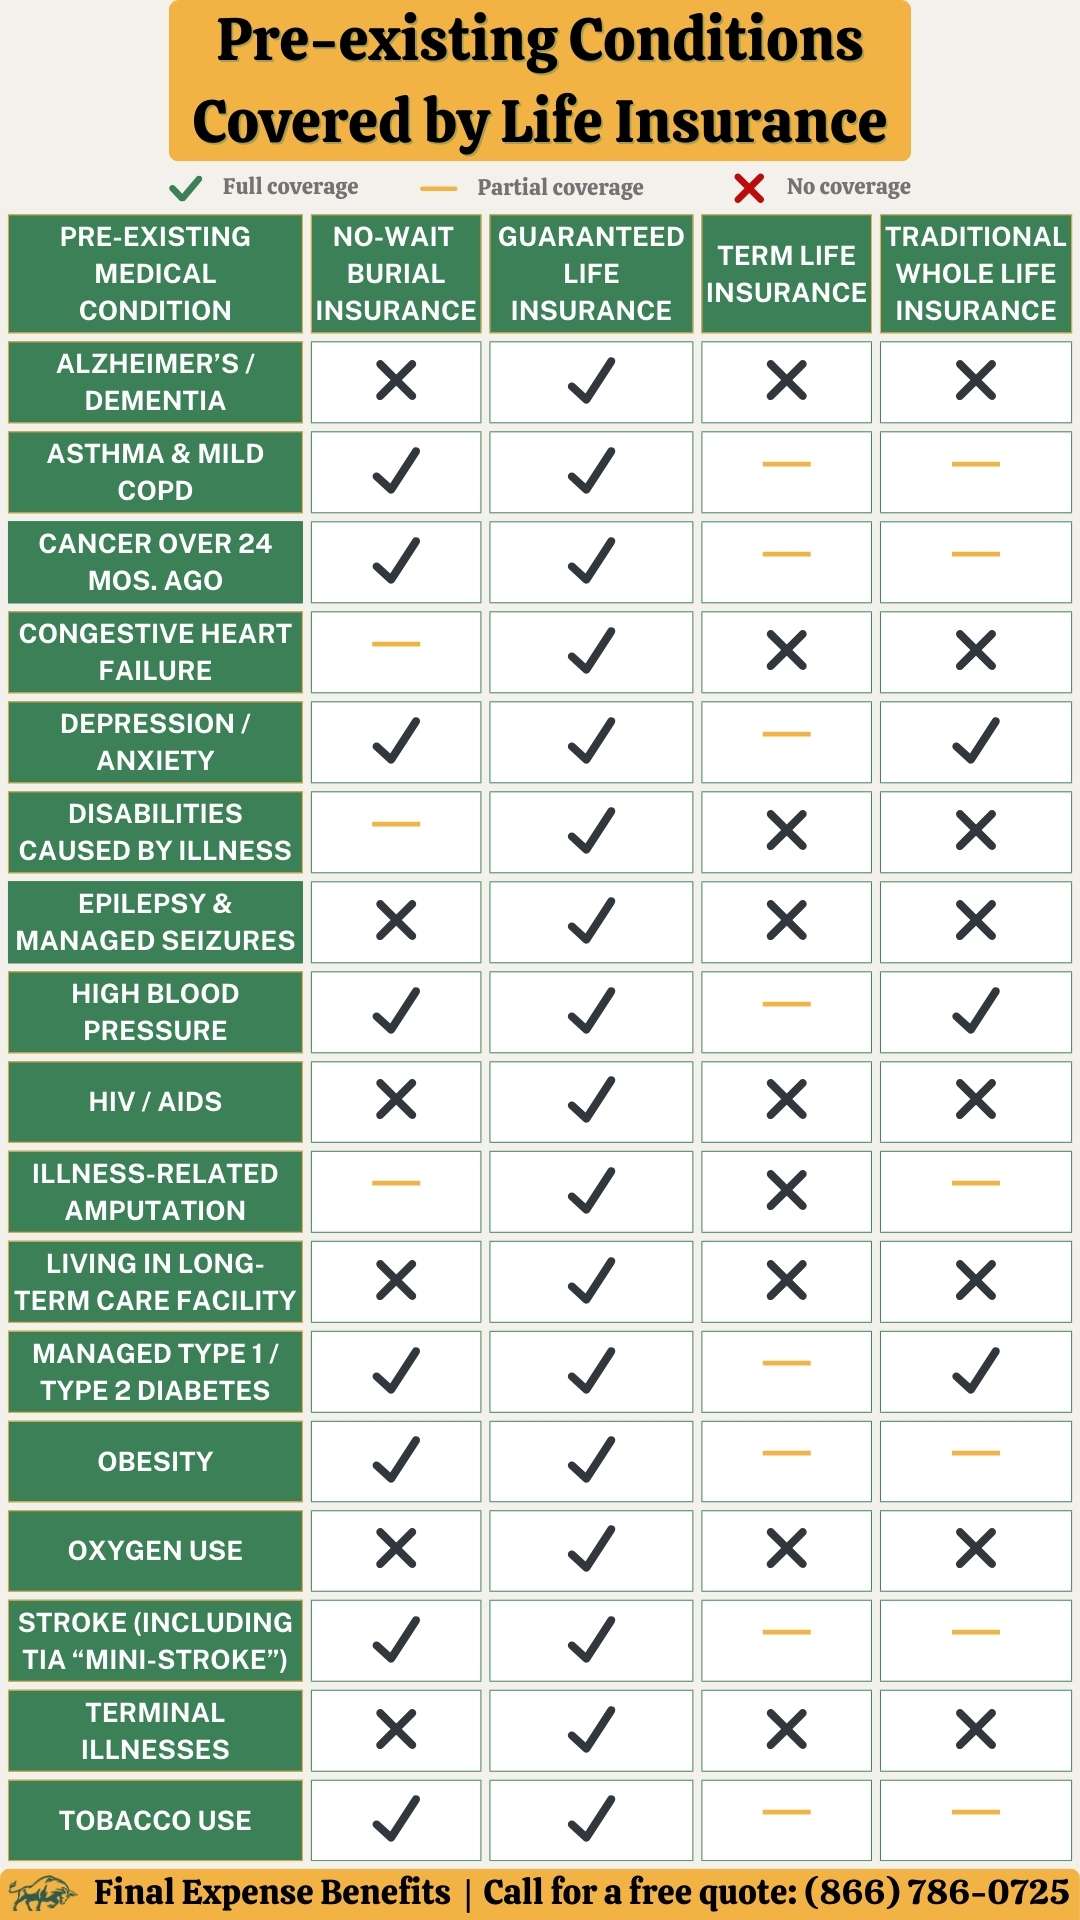
Each company has its own guidelines, but high-risk behaviors and conditions could include: Your existing health, past diagnoses, and how well severe conditions are handled are some of the primary elements insurance providers consider to figure out the danger in guaranteeing you. Some typical health conditions that typically fall under impaired danger include: Type 1 or Type 2 DiabetesHeart Disease or past heart attackHigh blood pressureCancer historyStroke or other neurological conditionsAsthma, COPD or other breathing issuesMental health conditions like depression or anxiety Besides health elements, your everyday habits may also impact your life insurance eligibility, approval, coverage amount and premiums.
Goldencare vs Harmony SoCalQualified Life Insurance for Vulnerable Profiles
These consist of: RoofersConstruction employees Pilots or air travel professionalsOil rig workersEmergency responders like firefightersWhen someone has one (or more) way of life factors or higher-risk conditions, it can impact the ability to get a policy and the premium pricing. Impaired danger life insurance works the very same way as a traditional policy.
: Well managed health conditions can assist you certify for lower rates in contrast to when insurers recognize patterns of neglect around medication, follow-up and treatment strategy. Cigarette smokers generally pay more premium in contrast to non-smokers. High-risk task functions suggest a higher chance of injury or mishaps, so exceptional expenses may increase.
Each insurance supplier has its own category system, however normally, the five categories are: People with excellent psychological and physical health, no weight problems, and total really few threat aspects. A little percentage of individuals certify for this.: General excellent physical and mental health however may have small risk, such as being somewhat obese.

A pre-existing health condition doesn't suggest you can't receive a life insurance coverage policy, however it just affects your available choices and pricing. Serious conditions such as cancer or a previous cardiovascular disease might position you in a higher-risk classification, so numerous individuals assume that they do not qualify for protection.
Integrating Life Insurance with Special Needs Planning
You still have alternatives which's when impaired risk life insurance coverage comes into the image. It lets you get coverage aligned to your risk aspect. Keep in mind: You can get life insurance protection with a medical condition. It's not constantly about the condition but what in fact matters is the severity, date of medical diagnosis and how it's managed.
Whether you have medical or non-medical high-risk elements, you still likely have options. However the secret is to match the policy options to your goals and current financial or personal scenarios. In case of impaired conditions, getting protection is simpler through no-medical-exam alternatives that may be simpler to certify for than totally underwritten term or irreversible life insurance policies.
It is a convenient choice for those with important health concerns looking for ensured approval however at a higher premium and lower coverage quantity. These policies consist of a waiting period of 2 to 3 years for non-accidental deaths before complete benefits apply. Streamlined concern policy type is another no-exam alternative that avoids physical laboratory tests, however involves evaluation through a health questionnaire and information checks.
Goldencare vs Harmony SoCalHere's how you can choose: Know the seriousness of your scenario to comprehend the schedule of policy options. Prevent assuming and instead make comparisons across several insurance companies. Not all insurance providers might offer similar coverage alternatives and guaranteed issue is not your only choice. Various insurance companies may assess threat differently, so constantly compare quotes.
Timing matters, so wait if your condition is improving to certify for much better alternatives later. Also, don't use with a lot of insurance providers at the very same time. Be sincere and transparent in your application to avoid claim rejections later. Even as an impaired-risk applicant, you may still have the ability to get protection.
Here are some suggestions you might follow: Guarantee that your condition is well managed and you follow the treatment plan. Keep your medical records handy to show stability in your health. Attempt giving up risky way of life habits like smoking cigarettes or alcohol consumption. Manage healthy way of life practices for weight management. Avoid applying right away after a condition is diagnosed.
Download and finish any suitable surveys suggested based off the preliminary questionnaire.
Life insurance coverage can be confusing, especially when it comes to underwriting. This post seeks to clarify life insurance underwriting by presenting clear, accurate details to help you make notified decisions.
How to Secure 2026 Impaired Risk Life Insurance
The majority of companies now provide fast underwriting options, which enable you to lessen the time necessary to get guaranteed. This means you could get protection the fastest way without compromising on thoroughness in its appraisal. Stay ahead of the market with exclusive function stories on the leading companies, professional insights and the most current news provided straight to your inbox.
While it's real that health plays a big function in underwriting, insurance providers consider numerous aspects, consisting of age, lifestyle, and household case history. Even if you have some health problems, you can still discover competitive rates customized to your situation. It's all about finding the ideal policy that matches your requirements and scenarios.
Each policy type, the quantity of protection you want, and the scrutiny will depend on it. For numerous policies, especially those with lower coverage quantities, the process can be easy and does not require much time. Some even use no-exam policies, which depend on existing medical records and other data and make decisions based upon that.

Latest Posts
Compassionate Coverage for Cancer Survivors
Updated Health Policies for Diabetic Applicants

Protecting the Legacy With Chronic Risks