All Categories
Featured
Why Specialized Planning Is Vital for Chronic Conditions
Navigating High Risk Insurance Underwriting in 2026
Advanced Planning for Specialized Risk Insurance Needs

Navigating High Risk Insurance Underwriting in 2026
Table of Contents
To the extent that income is distributed to the recipients, the recipients, not the trust, go through tax on that earnings. Earnings dispersed to a special needs beneficiary does not normally lead to a big tax effect, since recipients generally have restricted taxable earnings. Frequently, the special requirements recipient's income is listed below the limitation topic to earnings tax.
When the SNT keeps trust income, nevertheless, special tax guidelines apply that frequently lead to significantly higher income tax obligations. Under present law, the tax brackets for trusts and estates are compressed, which suggests that a trust reaches the greatest earnings tax rate (39.6 percent in 2013) once it has $11,950 of earnings (in 2013).
Using the 2013 tax tables, a trust will undergo earnings tax rates of 25 percent (the next tax bracket over 15 percent) on income over $2,450, while a single person (for example, the SNT beneficiary) would reach this tax rate just if the recipient had income over $36,250.

To make matters worse, SNTs with undistributed income in excess of $11,950 also will be subject to the 3.8 percent investment income surtax enforced by the Client Protection and Affordable Care Act of 2010, increasing the overall tax rate paid on income over $11,950 to 43.6 percent. Clearly, these high tax rates enforce pressure on trustees to make circulations, even when distributions may not be sensible provided the distinct situations of the special requirements beneficiary.
Special Needs Plan AdvisorTo fix the problem, the invested possessions within the trust would have to be shielded from present income tax (by being tax-deferred or tax-exempt), while still being offered for the trustee to disperse to the unique requirements individual when necessary. Life insurance coverage might be an ideal funding vehicle for SNTs, particularly because of the 2013 income tax boost and the imposition of the investment income surtax.
Navigating Impaired Risk Underwriting in 2026
Like the case with SNTs, the sponsors of executive postponed compensation strategies seek to avoid existing income tax on accumulations while maintaining access to the hidden investment properties so that circulations can be made as defined in the strategy. As a funding vehicle, life insurance supplies tax-deferred development (or tax-free growth, if the policy is in force at the death of the insured), yet permits the owner either to withdraw funds up to the amount of the basis in the policy, or obtain from the cash worth without earnings tax repercussions.
When SNTs are produced as inter-vivos trusts, life insurance coverage can be acquired on the life of the grantor, the grantor's spouse, or as a joint life policy on the couple. During the grantor's life, much of the recipient's monetary needs can be spent for directly by the grantor, therefore enabling the policy cash value inside the trust to collect while still being available for usage if essential.
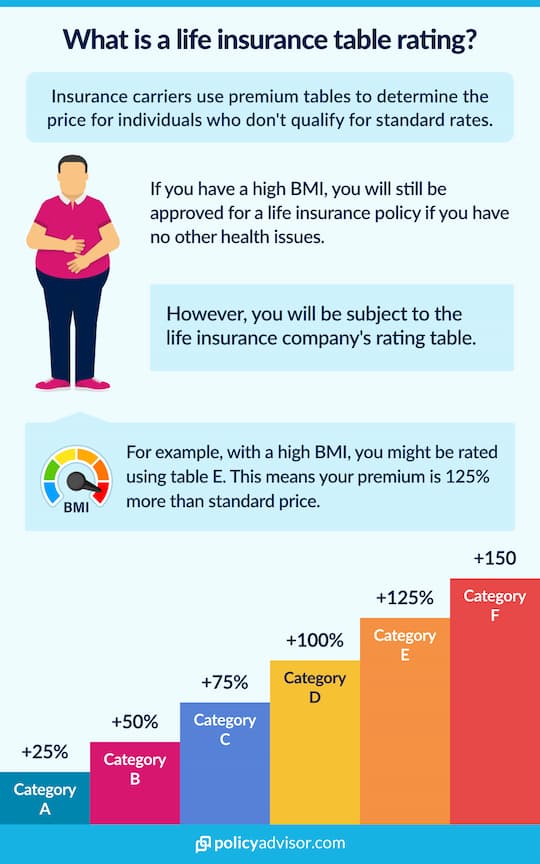
If the special requirements specific is insurable, an alternative approach is a life insurance policy bought on the life of the recipient. This method offers tax deferment on the underlying investments while allowing access to those investments for distribution when essential and changing the wealth consumed by the unique needs recipient with a tax-free life insurance coverage death benefit for the remainder recipients of the SNT.
Situations will vary, utilize of a maximum-funded, low-death-benefit variable universal life insurance coverage policy usually will be proper, especially when the forecasted time frame and the grantor's monetary risk tolerance are constant with equity-based returns. No matter the kind of policy, life insurance financing enables SNT grantors to make the most of the benefits readily available to unique needs children by denying the federal government of high earnings tax payments from the special requirements trust.
Mastering High Risk Insurance Underwriting in the US
This concern of The Voice is composed by Ken W. Shulman, Esq. who is a partner in the Boston, Massachusetts, workplace of Day Pitney LLP. Ken focuses his practice on estate planning and related concerns for families who have kids with disabilities and on elder law. He has actually served as a board member for a number of human service firms consisting of the Greater Boston ARC and presently works as a board member for the Asperger's Association of New England.
He is a co-author of Handling an Unique Needs Trust, People with Disabilities Press (2010 ). Ken typically serves as a trustee of unique requirements trusts at his customers' request. Ken is a member of the Unique Requirements Alliance, a national, non-profit organization dedicated to assisting individuals with impairments, their families, and the specialists who represent them.

Latest Posts

Compassionate Coverage for Cancer Survivors
Why Specialized Planning Is Vital for Chronic Conditions
Navigating High Risk Insurance Underwriting in 2026